Understanding the flexibility of payment options can make a significant difference for those shopping at Atacadão.
This guide introduces the installment systems available, assisting consumers who want more manageable monthly expenses.
Learning about these payment strategies can be helpful—especially for Brazilian families or entrepreneurs managing budgets.
Why Installment Payments Are Popular at Atacadão
Installment plans have become popular in Brazil, particularly in supermarkets like Atacadão. These payment solutions offer a way to control spending without sacrificing access to large-volume or essential purchases.
For many, spreading costs over time reduces financial stress. It doesn’t just help with personal cash flow; businesses also benefit, as they can adjust expenses based on sales cycles.
Understanding Atacadão’s Installment Payment System
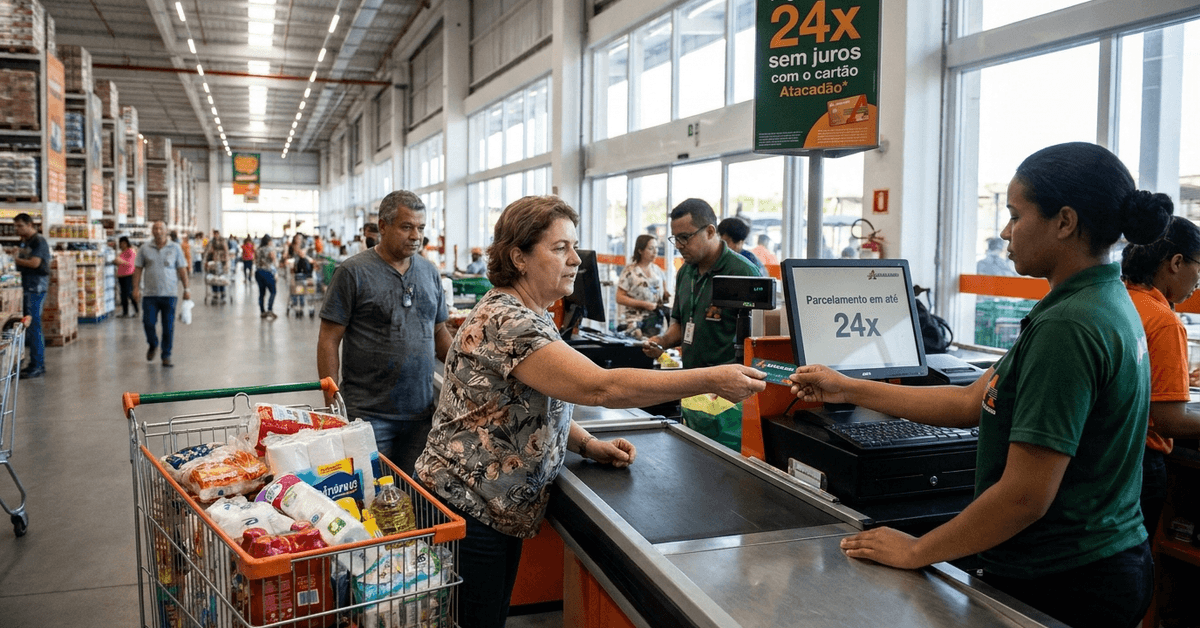
Atacadão allows eligible customers to pay their purchases in up to 24 installments. This practice, while not unique in Brazilian retail, stands out due to its generous payment timeline.
The system is designed for both individual and business shoppers, although certain rules and documentation may apply. Accepted cards, eligibility criteria, and purchase value minimums contribute to how payments get split into installments.
Who Can Use 24 Installments?
The ability to split payments into 24 installments is generally available to those who possess the official Atacadão card.
This store card is aimed at both private consumers and registered businesses, widening access. Requirements usually include legal age, proof of income, and a clear financial record.
How Does the Atacadão Card Work?
The Atacadão card functions like other store credit cards in Brazil. Cardholders may use it exclusively at Atacadão’s physical stores, and sometimes at partner locations.
A credit assessment usually determines the spending limit and eligibility for installment structures. The card can be applied for directly at the store or via the official Atacadão website card.
Eligibility Criteria and Required Documents
To join this payment method, one must meet certain requirements. Usually, this involves providing Brazilian CPF, proof of address, and proof of monthly income. The credit check seeks to ensure the applicant’s commitment to repayment.
For businesses, additional CNPJ documentation and proof of operation may be needed. Some applicants might find the requirements restrictive, while others consider them standard for credit line access.
Minimum Purchase Value for Installments
The minimum purchase value needed to qualify for installments varies. Atacadão typically sets a base threshold, so not every small basket or low-value transaction qualifies.
This practice is meant to balance the administrative costs associated with managing long-term payment plans with responsible lending. Checking current conditions at your local Atacadão branch or through official channels is always a good choice due to frequent policy updates.
Steps to Apply for the Atacadão Card
Those interested in accessing up-to-24 installment payments will start by applying for the Atacadão store card. This process is straightforward. The main steps involve submitting identification, providing required documents, and awaiting credit analysis.
Most card decisions—approval or rejection—are delivered quickly in-store or by email. Once approved, a card is provided and can be activated for purchases both online and in-person.
Documents Commonly Requested
- CPF (Cadastro de Pessoas Físicas)
- Proof of address (utility bill or bank statement)
- Proof of income (payslip, bank statement, or tax return)
- If applying for a business card: CNPJ, proof of company address, and operating permits
How the Installment Process Works In-Store
When checking out at Atacadão, eligible customers with a valid store card can request to pay in multiple installments. The cashier may provide information on available installment options, as well as interest rate disclosures.
Some installment schemes are interest-free for short terms, but longer plans, such as 24 months, may include financial charges. It’s necessary to review the terms, monthly fees, and total repayment cost before confirming the transaction.
Interest Rates and Charges
Interest rates applied to the Atacadão installment plan can vary based on current financial market rates and promotions. The official store documentation, receipts, and cardholder agreement always state the exact rates.
Some periods may feature promotional 0% interest rates for limited months, but longer-term plans, like 24 installments, typically carry a set APR. Evaluating the total payment before committing can help manage long-term costs.
Online and Digital Payment Possibilities
Atacadão is expanding its digital portfolio, offering a mobile app and online account access for cardholders.
Through these digital channels, users review payment activity, access statements, and sometimes request new installment plans or simulate future transactions. Security protocols align with industry standards, aiming to protect sensitive financial data.
Managing Installments Digitally
After enrollment, clients log in to their accounts through the official Atacadão app or via Itaú’s customer portal. From there, it’s possible to view upcoming payments, download invoices, and adjust due dates.
Many find the digital management features sufficient for day-to-day needs, adding flexibility for busy business owners or private shoppers.
Payment Deadlines and Default Risks
Each installment carries its deadline, appearing clearly on transaction receipts and digital statements. Missing an installment may result in additional interest or fees, which is rather standard in the Brazilian credit system.
The risk of negative credit reporting exists when multiple payments are delayed or missed, impacting future borrowing capacity. It’s advised to stay attentive to due dates—some set reminders or automate payments through the bank portal for added security.
Comparison: Atacadão vs. Other Brazilian Retailers
A brief look at the market shows that Atacadão’s up-to-24 installments is competitive. Many major supermarkets restrict plans to 6 or 12 months.
Others might match Atacadão for specific promotions, but few offer the consistency or access to business clients. Before starting any sizable purchase plan, it helps to compare interest rates and eligibility criteria across competing retailers.
Legal and Financial Considerations
Brazilian consumer protection laws regulate installment agreements, requiring clear disclosure of fees and terms. Atacadão and its banking partners are required to present transparent conditions.
Protestar (National Consumer Secretariat) offers additional guidance for those with disputes or questions on installment purchases. Staying informed about ongoing regulatory changes ensures better use of credit resources and fewer surprises.
Maintaining Financial Health While Using Installments
Stretching payments over 24 months certainly offers relief, but it’s important to avoid overcommitting. Fixed obligations may seem manageable initially but can pile up. Some individuals find it helpful to set a monthly spending limit or track all active installment plans to prevent financial stress.
It’s normal to pause and reconsider before adding a new long-term expense. Honest self-assessment and regular budget reviews are practical strategies.
Secure Your Budget: Final Thoughts
Choosing to pay in up to 24 installments at Atacadão can soften the impact of essential purchases. Still, it’s not a one-size-fits-all solution. It suits people with stable income and clear expense management strategies.
Using installments responsibly helps families and businesses—especially when combined with regular budget reviews. If interested in applying, visit the official Atacadão Card application portal for more details. A little diligence goes a long way toward keeping those monthly bills predictable and stress-free.